Flood Insurance in New Jersey: It's Not in Your Homeowners Policy
James Brazil lives in Mérida, Mexico. He founded Swift Agent Sites and studied Classics at the University of Mississippi.
Published · Updated
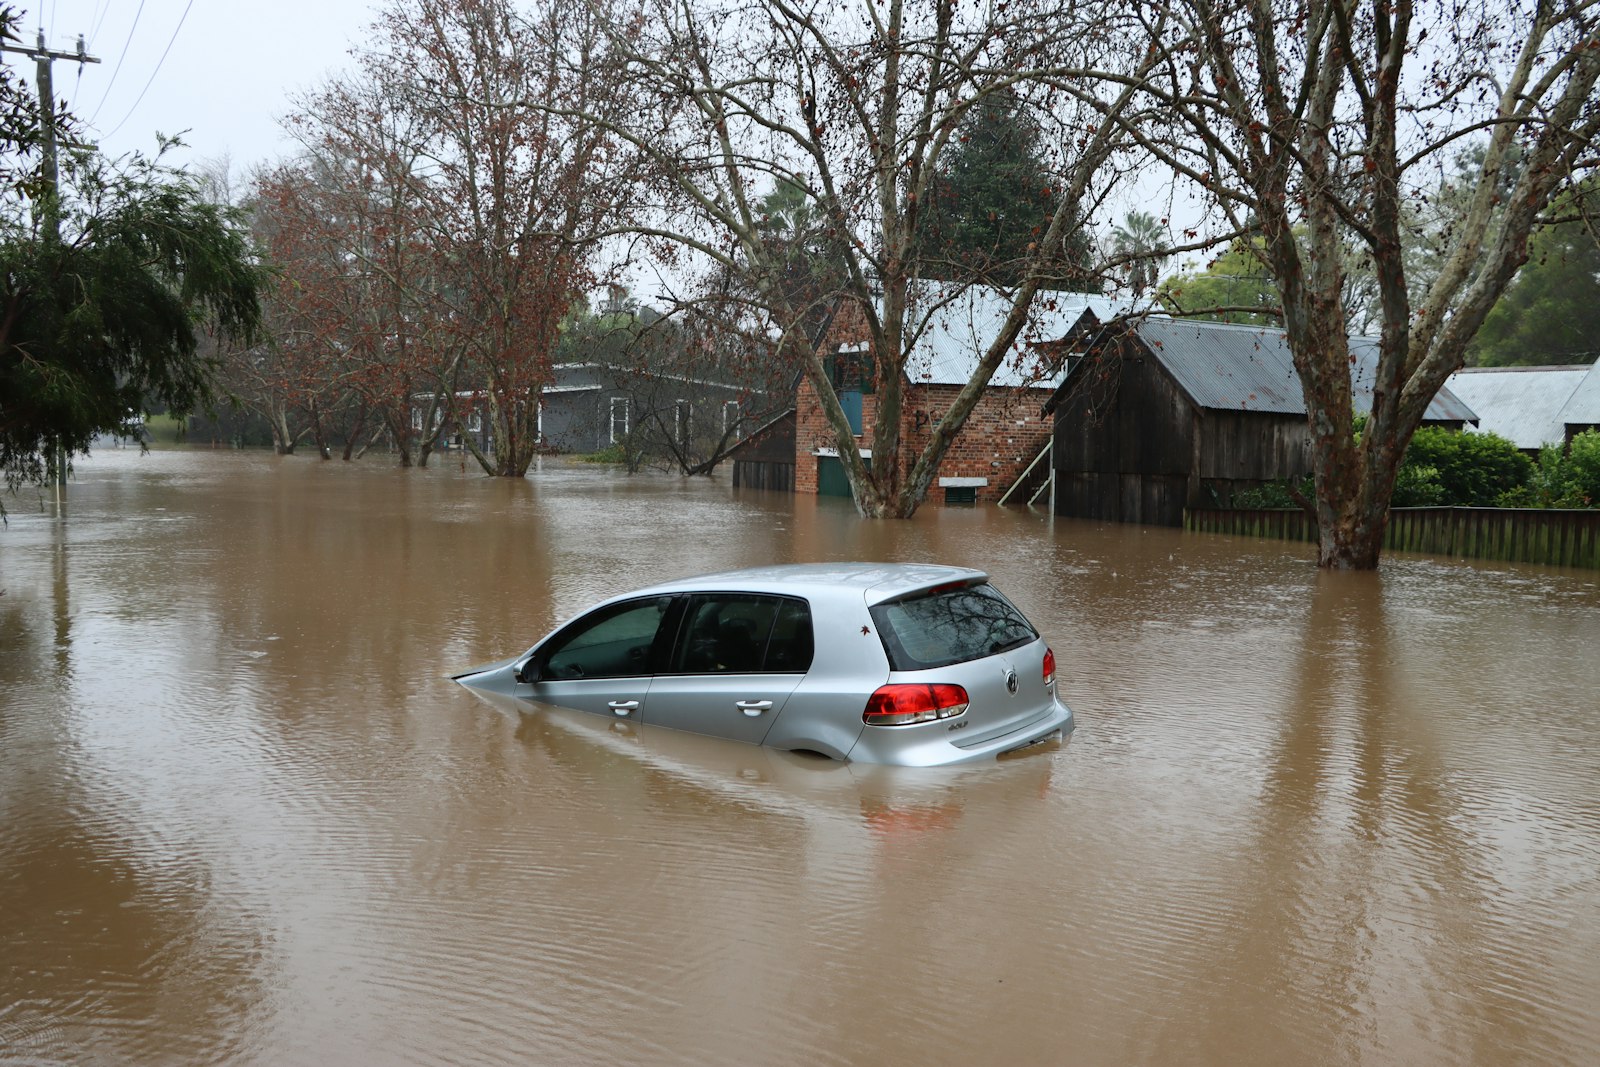
A standard New Jersey homeowners policy does not cover flood damage. If you want that protection, you need a separate flood policy, through the National Flood Insurance Program or a private insurer. Most NFIP policies have a 30-day waiting period, so buying coverage when a storm is already on the map is often too late.
Why this matters in New Jersey
Flood risk here is not limited to Ocean City or the Meadowlands. Coastal storm surge, overflowing rivers, and heavy rain in inland towns have all put water into basements and first floors. A lender will usually require flood insurance if the home is in a mapped high-risk zone. If it isn't, the requirement may not apply, but the water risk can still be real.
If you're buying a home, New Jersey also has a mandatory Flood Risk Addendum on the seller's property condition disclosure, and a Flood Risk Notification Tool at flooddisclosure.nj.gov. Use those as a starting point, then look at a flood map and an insurance quote. A disclosure is not a policy.
Don't assume a "water" endorsement on a homeowners policy is flood coverage. Sewer backup and sump-pump overflow are often separate, and they are not the same as an NFIP flood. Ask your agent, in writing, what is covered if a storm drain backs up, if a river leaves its banks, or if tidal water comes into the yard.
How long is the wait, and what does NFIP cover?
Most NFIP policies have a 30-day waiting period before coverage starts. There are exceptions, including some purchases made in connection with a loan, but you shouldn't count on an exception unless your agent or the program confirms the start date in writing.
A typical NFIP homeowners policy can insure the building and, separately, the contents. Official FloodSmart guidance says building coverage for a home can go up to $250,000, and contents coverage up to $100,000. Those two limits are chosen separately, and contents coverage is not automatic just because you insured the building.
Building coverage can include the structure and certain built-in items, such as electrical and plumbing systems, furnaces, water heaters, and permanently installed cabinets. Contents coverage can include furniture, clothing, and electronics kept inside the home.
NFIP policies also leave things out. They generally do not cover:
- Temporary housing and additional living expenses while the house is repaired.
- Cars and most self-propelled vehicles.
- Personal property kept in basements, in many cases.
- Property outside the insured building, such as decks, fences, and landscaping.
- Currency and certain valuable papers.
If your house would cost more than $250,000 to rebuild, or you need living-expense coverage after a flood, ask about a private flood policy or excess coverage. Compare deductibles, waiting periods, and what each policy pays for a basement or a finished lower level, which is a common New Jersey question.
How should you decide whether to buy it?
- Look up the address on FEMA's flood map and on flooddisclosure.nj.gov if you're buying or selling.
- Think about nearby creeks, rivers, storm drains, and, at the Shore, tidal flooding even on sunny days.
- Price what it would cost to replace flooring, drywall, a furnace, and a water heater after a few feet of water.
- Compare an NFIP quote with any private flood quote, including the waiting period.
- If you rent, consider contents-only flood coverage. A landlord's policy usually does not replace your furniture.
A policy that costs a few hundred or a few thousand dollars a year is easier to judge once you've priced a single interior rebuild. Don't wait for a hurricane watch or a river forecast to start that math.
If you already have a mortgage in a high-risk zone and the lender escrowed flood insurance, still read the declarations page. Confirm the building and contents limits, the deductible, and the expiration date.
If you live in a building with a homeowners association, ask whether the association carries flood coverage on the building and what, if anything, you still need for your unit and your belongings. A master policy can leave a large gap at the unit level.
After you buy a policy, put the renewal date on your calendar. A lapse followed by a new 30-day wait is a painful way to learn the coverage was not continuous.
FAQ
Does a standard New Jersey homeowners policy cover flood damage?
No. You need a separate flood policy, available through the National Flood Insurance Program or a private insurer.
How long do I have to wait for NFIP coverage to start?
Most NFIP policies have a 30-day waiting period. Some exceptions exist, including certain loan-related purchases. Confirm the start date in writing.
Do I need flood insurance if I'm not in a floodplain?
You may not be required to buy it by a lender, but you can still flood. Inland rivers and heavy rain have flooded New Jersey homes outside high-risk zones.
Can I buy more than the NFIP $250,000 building limit?
You may be able to buy private or excess flood coverage. Ask a licensed agent to compare options, including living expenses, which a standard NFIP policy generally does not include.
Next step
Ask a licensed local agent to quote a flood policy on your address, including the waiting period and whether contents and additional living expenses are covered. If you're buying a New Jersey home, also review the seller's Flood Risk Addendum and the state's flooddisclosure.nj.gov tool.
Sources: National Flood Insurance Program, buy a flood insurance policy; New Jersey Flood Risk Notification Tool; Division of Consumer Affairs, Seller's Property Condition Disclosure Statement instructions (PDF); DOBI, auto and property consumer information.
This is general information for New Jersey. It is not a recommendation to buy, drop, or switch a specific policy. Confirm current details with the insurer or a licensed agent who knows your situation.
Agents who publish a lightly edited version on their own domain should set a canonical tag pointing to this URL.
List your business on the New Jersey hub, free: Insurance